
Effective project management is crucial for ensuring that organizations achieve their objectives while efficiently utilizing resources. Whether managing large-scale construction projects, IT implementations, or strategic initiatives, keeping track of finances, resources, and timelines is essential. One area that project managers must increasingly consider is how leases, especially operating lease accounting, can impact the financial health and performance of a project.
- 1Operating leases now sit on the balance sheet. Under ASC 842 and IFRS 16, leased project equipment adds a right-of-use asset and a lease liability, except for leases of 12 months or less.
- 2Lease cost hits your budget every month. Under ASC 842 an operating lease shows one straight-line cost over the term, so plan it across the whole schedule, not just at signing.
- 3Match the lease to the schedule. Only 8.5% of large projects hit both budget and schedule, so price extensions and early exits before you sign.
- 4Bring finance in early. An in-house finance team or an outside accountant can show how a lease changes debt-to-equity before the project commits.
Operating lease accounting, which governs how companies account for leases under standards like ASC 842 in the United States and IFRS 16 in many other countries, plays a significant role in the financial planning and execution of projects. The ability to accurately track and report leased assets, whether equipment, office space, or technology, can influence project decisions, timelines, and budget allocation. This article will examine the intersection of operating lease accounting and project management, highlighting how project managers can utilize this financial tool to improve project outcomes.
Understanding Operating Lease Accounting
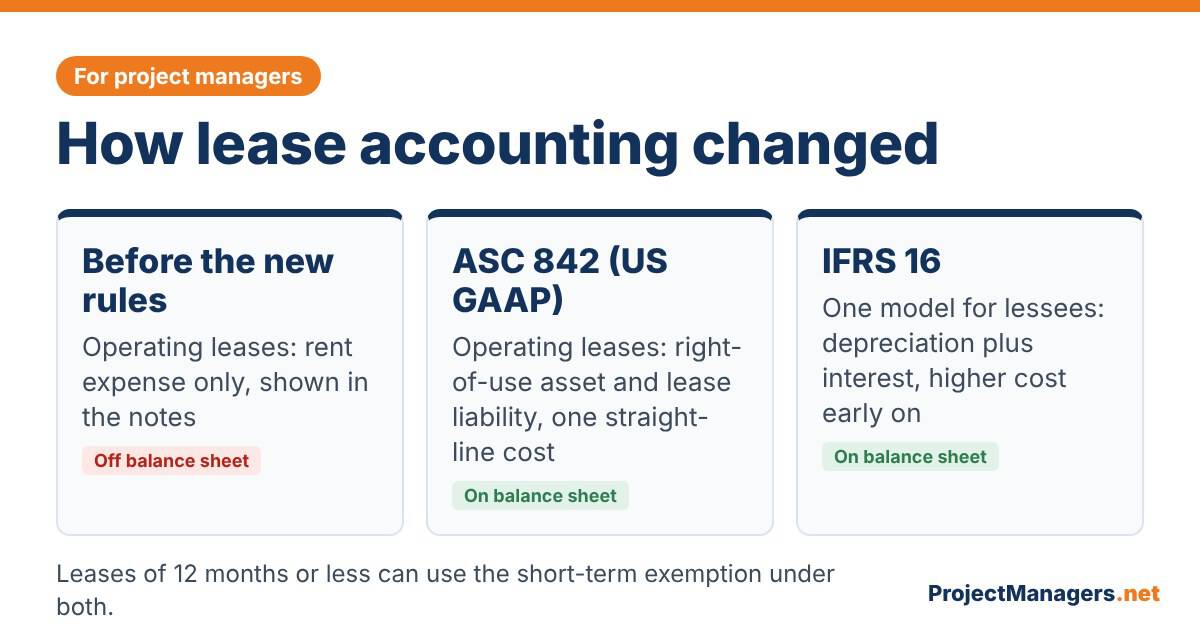
Before diving into how operating lease accounting impacts project management, it’s essential to grasp the concept itself. In accounting terms, an operating lease is a contract that allows the lessee (the company) to use an asset without transferring ownership. Unlike capital leases (now known as finance leases), operating leases were kept off the balance sheet until recent accounting standard changes. ASC 842 now requires companies to recognize lease liabilities and right-of-use (ROU) assets on their financial statements. Outside the United States, IFRS 16 goes further and treats almost all of a lessee’s leases like finance leases.
Operating leases are typically used for assets that a company only needs temporarily or doesn’t plan to own outright, such as office space, equipment, or vehicles. These leases provide flexibility, allowing companies to operate without the upfront costs associated with purchasing assets. However, under ASC 842, even operating leases must now be accounted for on the balance sheet (except leases of 12 months or less, when the company elects the short-term exemption), impacting financial statements and project management calculations.
This short video gives a quick overview of how ASC 842 works:
Video: Leases: Overview of ASC 842, by GAAP Dynamics (under 2 minutes). Watch it on YouTube.
Real-life example
Over US$3 trillion of leases were missing from balance sheets
When it published IFRS 16, the IASB said that listed companies using IFRS or US GAAP had about US$3.3 trillion of lease commitments, and that more than 85% of them did not appear on balance sheets. Over 14,000 of the 30,000 listed companies in its sample disclosed off-balance-sheet leases in their 2014 annual reports. For project managers, that debt is now visible to lenders and executives, so every leased crane, server or office floor shows up in the numbers they review.
Source: IFRS Foundation, IASB shines light on leases (January 2016)
Expert view
“These new accounting requirements bring lease accounting into the 21st century.”
Hans Hoogervorst, then Chairman of the IASB (source)
By the numbers
The Impact of Lease Accounting on Project Management

Operating lease accounting intersects with project management in several important ways, particularly when it comes to budgeting, resource allocation, and financial reporting. Project managers are tasked with juggling various components to ensure the successful completion of a project, and the financial treatment of leases can significantly impact project costs and timelines. Let’s take a closer look at some key considerations:
1. Budgeting for Leased Equipment and Assets
Leased assets, such as machinery, software, or vehicles, are often critical to the success of a project. However, understanding how the costs associated with these leases will be treated under the organization’s financial structure is crucial for accurate budgeting. Under ASC 842, the cost of an operating lease is recognized as a single, generally straight-line expense over the lease term, meaning that project managers need to account for these costs in both the short and long term.
The ability to spread lease costs over the life of a project can offer financial flexibility. However, with the ASC 842 standard requiring both assets and liabilities to be reported on the balance sheet, this can also affect the company’s debt-to-equity ratio and other financial metrics, influencing decision-making in project planning.
Project scenario (illustrative)
One leased excavator, two accounting views
A construction project leases a 30-ton excavator for 18 months at $9,500 a month, plus a $2,000 fee. Under ASC 842, at a 7% discount rate, the company records a lease liability of about $162,800 and a right-of-use asset of about $164,800 when the lease starts, and the project budget carries an operating lease cost of about $9,600 a month. Under IFRS 16, the same lease shows depreciation plus interest, so the cost is higher in the first months and lower later.
Illustrative figures from the Lease vs Buy Calculator below. Payments are assumed at the start of each month.
By the numbers
Dec 15, 2018
ASC 842 applies to public companies for fiscal years beginning after this date
Dec 15, 2021
ASC 842 applies to private companies for fiscal years beginning after this date
12 months
leases this short or shorter can use the short-term exemption under both standards
2. Cash Flow Management
Effective cash flow management is a cornerstone of project management, and leasing is often used as a strategy to preserve cash. Leasing enables companies to pay for only the usage of an asset, not its full purchase price, which can free up cash for other aspects of a project, such as hiring, research, or marketing.
Under operating lease accounting, project managers need to track lease payments and account for the timing of these payments within the broader project timeline. Proper cash flow management involves scheduling these payments to align with project milestones and ensuring that the lease terms support the overall financial health of the project.
3. Risk Management
Leasing assets can offer flexibility, but it also introduces risk, especially when the terms of the lease don’t align with the project’s needs. For instance, a project that runs over schedule might require the extension of lease terms, resulting in additional costs. On the other hand, terminating a lease early can lead to penalties or loss of the asset before the project is complete.
Project managers must carefully assess every lease agreement to mitigate these risks. Understanding the implications of operating lease accounting, particularly how lease liabilities are recognized and managed, can help project managers anticipate potential pitfalls and ensure they have contingency plans in place.
Real-life example
Most big projects run late, and their leases run late with them
Bent Flyvbjerg and Dan Gardner looked at more than 16,000 projects. Only 8.5% hit both their budget and their schedule, and just 0.5% delivered on budget, on time and with the benefits promised. When the schedule slips, a lease that ends on the planned date has to be extended, often at a higher rate. A lease that outlasts the project can carry an early-exit penalty instead.
Source: Flyvbjerg and Gardner, Harvard Business Review, January-February 2023
Expert view
“Think slow, act fast.”
Bent Flyvbjerg and Dan Gardner, How Big Things Get Done (2023)
By the numbers
Key Considerations for Project Managers
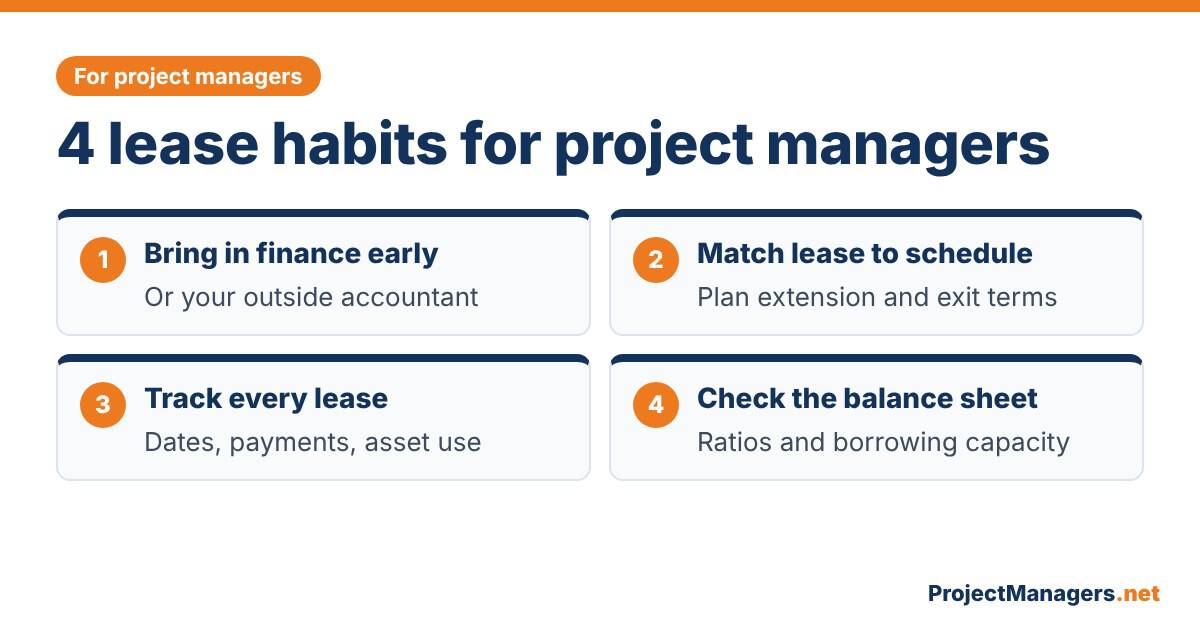
Incorporating operating lease accounting into project management involves more than just financial reporting. It requires a holistic understanding of how leases affect the entire lifecycle of a project, from initiation to completion. Here are some best practices that project managers can adopt to better integrate lease accounting into their processes:
- Early Involvement of Financial Teams: To ensure accurate budgeting and financial forecasting, project managers should involve the company’s finance team early in the project planning process. For businesses without a dedicated in-house finance team, working with an experienced accountancy firm can provide the same level of financial oversight, ensuring lease costs, cash flow implications, and balance sheet impacts are properly understood before commitments are made. Finance teams can provide insights into how leases will be accounted for under operating lease accounting rules, helping project managers avoid unexpected costs or financial setbacks later in the project.
- Align Lease Terms with Project Timelines: A mismatch between lease terms and project timelines can lead to cost overruns or delays. Project managers should negotiate leases that align closely with the project’s schedule, including provisions for extensions or early termination if necessary. Flexibility in lease agreements can provide critical support for projects that encounter unexpected challenges.
- Use Technology to Track Leases: Many of today’s project management tools can be set up to track lease agreements, payment schedules, and asset usage. Leveraging software solutions that integrate financial data, project timelines, and lease information can help project managers stay on top of costs and ensure that leased assets are used effectively throughout the project.
- Consider the Long-Term Impact on Financial Statements: While leasing offers short-term financial flexibility, project managers need to be mindful of how operating lease accounting affects the company’s financial position over time. Under ASC 842, operating leases now appear on the balance sheet, which can impact the organization’s financial ratios and borrowing capacity. Understanding these implications allows project managers to make more informed decisions about leasing versus purchasing assets for long-term projects.
By keeping these considerations in mind, project managers can effectively navigate the complexities of lease accounting while ensuring that their projects stay on track and within budget.
Lease vs Buy Calculator: Test Your Project’s Options
Use this free Lease vs Buy Calculator to see what a leased asset really costs your project before you sign. It compares leasing and buying in cash and in present value, tests what happens if the project runs late, and shows the lease liability, right-of-use asset and debt-to-equity change that ASC 842 puts on the balance sheet. It opens with a construction example, so you can see how it works before you enter your own numbers.
- Enter the project length, a possible delay and your company’s cost of borrowing.
- Add the purchase price, resale value and monthly upkeep if you buy.
- Add the lease term, monthly payment, upfront fee, extension premium and early-exit penalty if you lease.
- Optionally, add total liabilities and equity to see the debt-to-equity change.
- Copy the summary or download the CSV and share it with your finance team or accountant.
Lease vs Buy Calculator
Opens with a construction example. Change any number and the results update. Nothing you type is stored or sent.
Project
If you buy
If you lease
Balance sheet (optional)
Lease cost for the project
Buy net cost
Better option
Compared in present value
Cash on day one
Lease vs buy
ASC 842 view of the lease at signing
Lease liability
Right-of-use asset
Operating lease cost
Debt-to-equity
Cumulative cash out by month:LeaseBuy (drops at resale)
Estimate only, not accounting advice. Payments are assumed at the start of each month, and the resale value falls evenly over the project. Confirm the lease treatment with your finance team or accountant.
The Future of Lease Accounting and Project Management

As businesses continue to adopt more flexible and scalable models, including leasing rather than purchasing assets, the intersection of operating lease accounting and project management will only become more pronounced. The transition to ASC 842 has already shifted how organizations think about leasing, and as companies continue to rely on leasing for operational efficiency, project managers will need to adapt to the new financial landscape.
Looking ahead, technological advancements in lease management software and project management tools will likely make it easier for project managers to account for leased assets and integrate lease-related costs into broader project plans. These tools will streamline communication between project teams and finance departments, making the financial implications of leases more transparent and easier to manage.
For companies that rely on an outside accountant rather than an in-house finance team, much of this already happens through accounting practice management software, where firms request lease agreements, share financial statements, and collect client approvals in one secure place instead of long email threads.
Lease Accounting Facts Worth Checking
Nine common claims about lease accounting and project risk, checked against the standards and primary sources.
| # | You may hear | What the sources say | Source |
|---|---|---|---|
| 1 | Operating leases still stay off the balance sheet. | Since ASC 842 took effect (fiscal years beginning after December 15, 2018 for public companies and after December 15, 2021 for private companies), lessees record a right-of-use asset and a lease liability for operating leases. | Deloitte, ASU 2020-05 |
| 2 | ASC 842 is the lease rule everywhere. | ASC 842 is part of US GAAP. Companies reporting under IFRS follow IFRS 16, effective January 1, 2019. | IFRS Foundation |
| 3 | IFRS 16 has operating leases too. | For lessees, IFRS 16 uses a single model: almost all leases are accounted for like finance leases. ASC 842 keeps both finance and operating leases. | Deloitte, Appendix B |
| 4 | Every lease must go on the balance sheet. | Both standards allow a short-term exemption for leases of 12 months or less. IFRS 16 also lets lessees exempt low-value assets, about $5,000 or less when new. | Deloitte, Appendix B |
| 5 | Off-balance-sheet leases were a small issue. | Before IFRS 16, listed companies using IFRS or US GAAP had about US$3.3 trillion of lease commitments, and over 85% were off the balance sheet. | IFRS Foundation |
| 6 | An operating lease is expensed like a loan, with more cost up front. | Under ASC 842, an operating lease shows a single lease cost, generally straight-line over the lease term. The front-loaded pattern applies to finance leases and to IFRS 16. | FinQuery |
| 7 | Operating lease payments are financing cash flows under ASC 842. | Under ASC 842, operating lease payments are presented as operating activities in the cash flow statement. | Deloitte, Appendix B |
| 8 | Private companies must use their borrowing rate to value leases. | Under ASC 842, companies that are not public business entities may elect, by class of asset, to use a risk-free rate. IFRS 16 has no equivalent option. | Deloitte, Appendix B |
| 9 | Most large projects finish on time and on budget. | Only 8.5% of more than 16,000 projects hit both budget and schedule, so plan lease extensions and exits. | Flyvbjerg and Gardner, HBR 2023 |
Sources checked November 6, 2026.
Conclusion: Balancing Lease Accounting with Project Success
Incorporating operating lease accounting into project management isn’t just a matter of adhering to new accounting standards; it’s about optimizing resources, managing risks, and ensuring long-term financial sustainability. Leased assets can offer significant advantages for projects, allowing organizations to operate with greater flexibility and preserve capital, but understanding how these leases affect financial performance is crucial for effective project management.
By integrating lease accounting into the project planning process, project managers can make more informed decisions about resource allocation, budgeting, and risk mitigation. This not only ensures compliance with accounting standards but also enhances the overall success of the project, delivering better outcomes for both the organization and its stakeholders.
Operating Lease Accounting FAQ
What is an operating lease in project management?
An operating lease lets a company use an asset, such as equipment, vehicles, software or office space, for part of its life without owning it. Project managers use operating leases to get assets for the length of a project without a large purchase on day one.
How did ASC 842 change operating lease accounting?
Before ASC 842, operating leases were shown only as rent expense and in the notes. Under ASC 842, the company records a right-of-use asset and a lease liability on the balance sheet, while the income statement still shows one straight-line lease cost. Leases of 12 months or less can use the short-term exemption.
What is the difference between ASC 842 and IFRS 16?
ASC 842 is the US GAAP standard and keeps two lease types for lessees: finance and operating. IFRS 16, used in many other countries, treats almost all lessee leases the same way, with depreciation and interest instead of a single straight-line cost. IFRS 16 also has an exemption for low-value assets.
Should a project lease or buy equipment?
It depends on how long the project needs the asset, the resale value, upkeep, your cost of borrowing and the risk of delays. Leasing usually needs far less cash up front, while buying can cost less over a long project. Use the Lease vs Buy Calculator on this page to compare both, then confirm the accounting with your finance team or accountant.
Why does lease accounting matter to project managers?
Lease terms decide when costs hit the project budget, how much cash the project needs, and what happens if the schedule slips. Because leases now appear on the balance sheet, they can also change debt-to-equity and borrowing capacity, which executives watch when they approve projects.
Suggested articles:
- Top 10 Advantages of Using Construction Accounting Software
- Smarter Cost Tracking to Prevent Project Budget Overruns
- Top Methods for Analyzing and Optimizing Your Cash Flow

Daniel Raymond, a project manager with over 20 years of experience, is the former CEO of a successful software company called Websystems. With a strong background in managing complex projects, he applied his expertise to develop AceProject.com and Bridge24.com, innovative project management tools designed to streamline processes and improve productivity. Throughout his career, Daniel has consistently demonstrated a commitment to excellence and a passion for empowering teams to achieve their goals.